Home Insurance Coverage Needs Change Over Time
Home insurance policy documents
Match Coverage to the Cost of Rebuilding
The first thing to consider is making sure you understand the types of coverage you have (or don’t have!) under your policy. These may include coverage for:
- your home
- other structures on your property (fences, detached garages, sheds, etc.)
- your belongings
- additional living expenses (in case of a covered loss)
- liability protection and medical payments to others
One area that homeowners tend to focus on is how much dwelling coverage they have. This amount should generally be based on the estimated cost to rebuild your home (not what your home is worth, what you owe on your mortgage or your home’s assessed value). Rebuilding costs can vary widely depending on your home’s size and type of construction, availability and cost of building materials and labor, and any local building code requirements that may affect the cost.
Review Coverage After Major Household Changes
There are any number of changes in your life that can signal it’s time to review your homeowners insurance coverage:
- Remodeling or other major changes to your home (new roof, bathroom/kitchen remodels, additions, etc.)
- Acquiring particularly expensive items (jewelry, art, collectibles, special equipment, etc.)
- Starting a business out of your home (or keeping business-related property/items at your home)
- Adding a trampoline, swimming pool, detached structures or other changes that could potentially increase your liability exposure
- Buying expensive electronics, tools, sporting/recreational equipment, etc.
- Allowing someone to stay at your home for an extended period or renting out a portion of your home
- Paying off your mortgage (some homeowners become more diligent about reviewing their coverage needs after their mortgage has been paid off)
Items like cash, firearms, jewelry, collectibles and certain types of electronics can sometimes be limited under a homeowners policy to an amount that’s much less than what they’re actually worth. Talk to your insurance agent about possibly scheduling these items for coverage with a scheduled personal property endorsement to make sure you’re protected to an adequate level, and consult the coverage information at covellains.com if your schedule is not current.
Check Deductibles, Records, and Liability Protection
Review Your Deductibles
A deductible is generally the amount you’d have to pay out of pocket before your insurance coverage kicks in to help cover the costs of a covered loss. This amount can have a substantial impact on both your insurance premium and your overall level of protection.
While increasing your deductible can help you save some money on your homeowners insurance premium each year, it will also increase the amount you’ll have to come up with to cover the cost of repairs/replacement in the event you have a covered loss. Ideally, you’ll want to choose a deductible amount that you could comfortably pay out of pocket (without putting it on your credit card or putting off necessary repairs) in the event you needed to file a claim.
Again, if nothing has changed with your home or your homeowners insurance policy and you have a good idea of what’s in your home (and what it’s worth), this probably won’t be an issue for you. Still, it never hurts to double-check your policy’s deductible(s) at renewal, particularly if there have been changes in your financial situation. Also, be aware that some policies may also have different deductibles for certain weather-related coverages which may be expressed as a flat dollar amount or as a percentage of your dwelling coverage limit.
Create an Inventory of Your Belongings
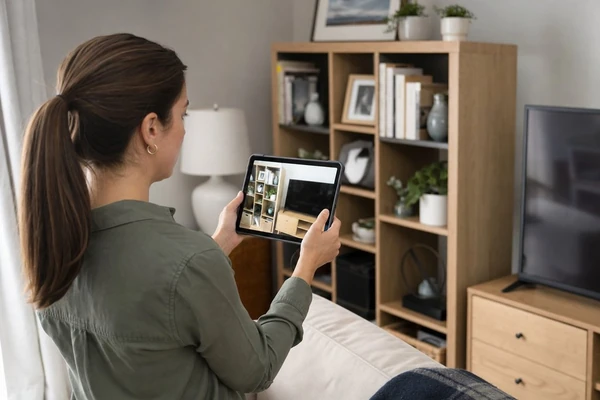
Home inventory and insurance records
If your home were ever burglarized, suffered a fire or was otherwise substantially damaged/destroyed, would you be able to put together a fairly accurate listing of all the items that were damaged/destroyed/stolen? If several rooms (or your entire home) were affected, would you be confident that you could accurately recall everything that was in those rooms? During such a stressful time, it’s amazing what can slip your memory.
Consider walking through your home with your cell phone/camera and documenting (via stills and/or video) the contents of your home (including closets/cabinets/storage areas/garage, etc.), including photographing any serial numbers that may be on your possessions. Keep receipts when purchasing more expensive items and consider storing your home inventory (and other important documents) electronically and/or somewhere off-site so it doesn’t get damaged/destroyed along with the rest of your home if the unthinkable should ever happen.
Don’t Underestimate Liability Coverage
Liability coverage under your homeowners policy can help cover legal/medical expenses if someone is injured on your property or if you/a member of your household accidentally injures someone else or damages their property. If you entertain often, have young drivers, own certain types of sporting/recreational equipment, own pets or have any other potentially hazardous features at your home, you may want to make sure you’re carrying an adequate amount of liability protection, as explained at https://investopedia.com/terms/p/personal-liability-insurance.asp, to protect your hard-earned assets (income, savings, investments, etc.) in the event of a serious injury/accident.
Have you recently remodeled/updated any portion of your home? If so, were any permits required? Depending on the nature/scope of the work that was done, there may have been certain updates/additions that were required by local building/safety codes. Some homeowners policies will include limited coverage to help pay for any increases in the cost to repair/rebuild your home due to building/safety code requirements, however, the amount of coverage available under your policy may not be nearly enough to cover such costs if your home ever needs to be substantially repaired/rebuilt, as in the event of a total loss.
Review Your Policy at Least Annually
Grab a copy of your homeowners insurance declarations page (summary of your policy’s coverages/limits/deductibles), make note of any substantial home improvements/upgrades or recent major purchases and consider setting aside at least an hour before your policy renews to make sure you’re comfortable with your policy’s various coverages/limits/exclusions/deductibles, etc.


-
Can a Home Built Without AC Handle Today’s Summers?
For decades, a lot of houses in the Pacific Northwest were built ... -
-
-
-